The starting point: agencies could not sell ancillaries
Most airline tickets are sold by travel agencies: about 80% for full-service carriers, about 70% for low-cost carriers and about 90% for foreign airlines. Yet until 2019, travelers could not buy seat selection or extra baggage on agency sites; they had to buy them separately from the airline or at the airport.
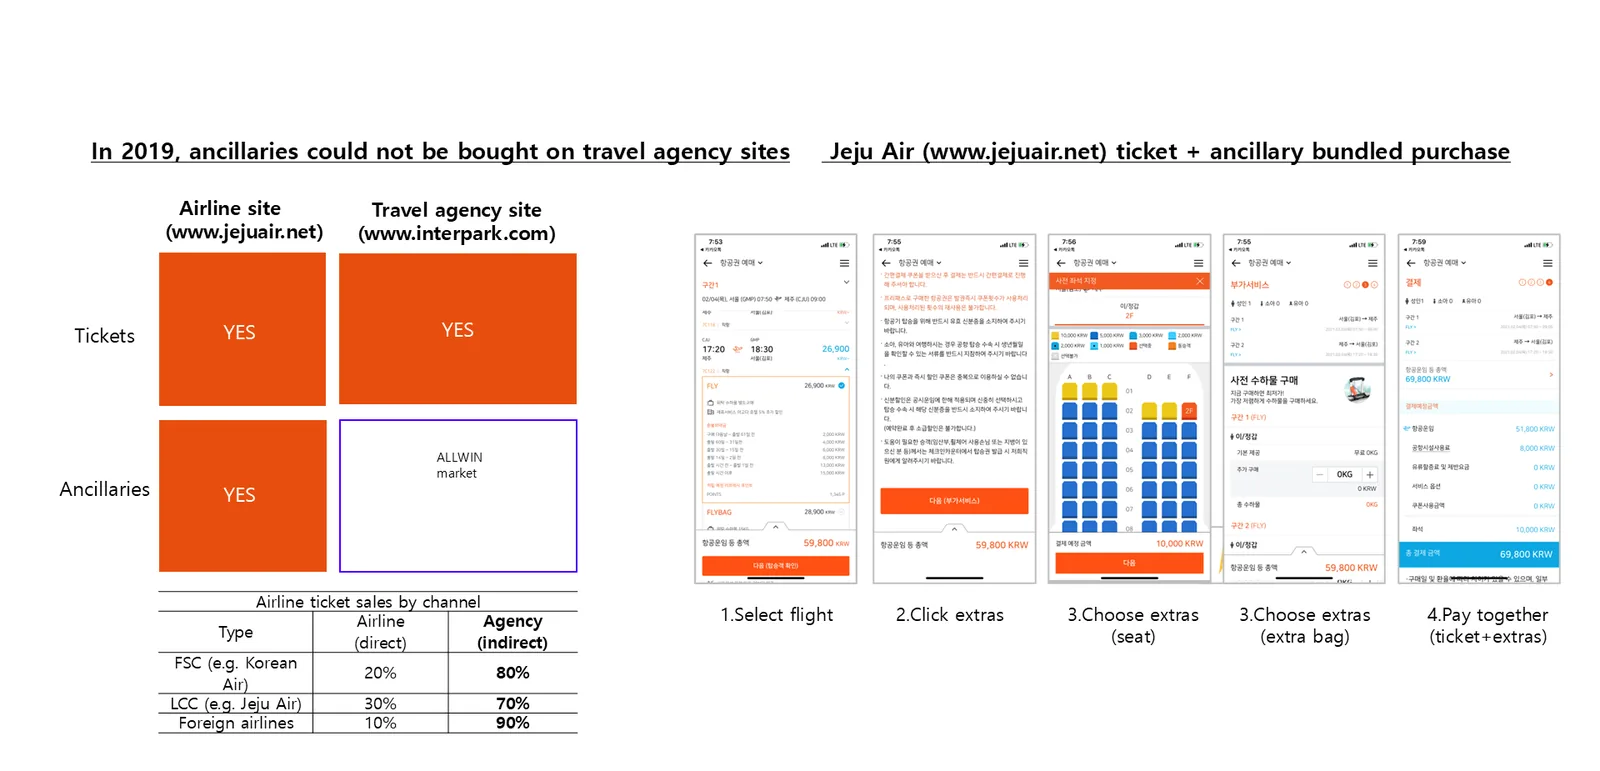
| Type | Airline direct | Agency (indirect) |
|---|---|---|
| FSC (full-service carriers) | about 20% | about 80% |
| LCC (low-cost carriers) | about 30% | about 70% |
| Foreign airlines | about 10% | about 90% |
Ticket sales by channel (from our 2021 partnership deck)
Our place: between suppliers and sellers
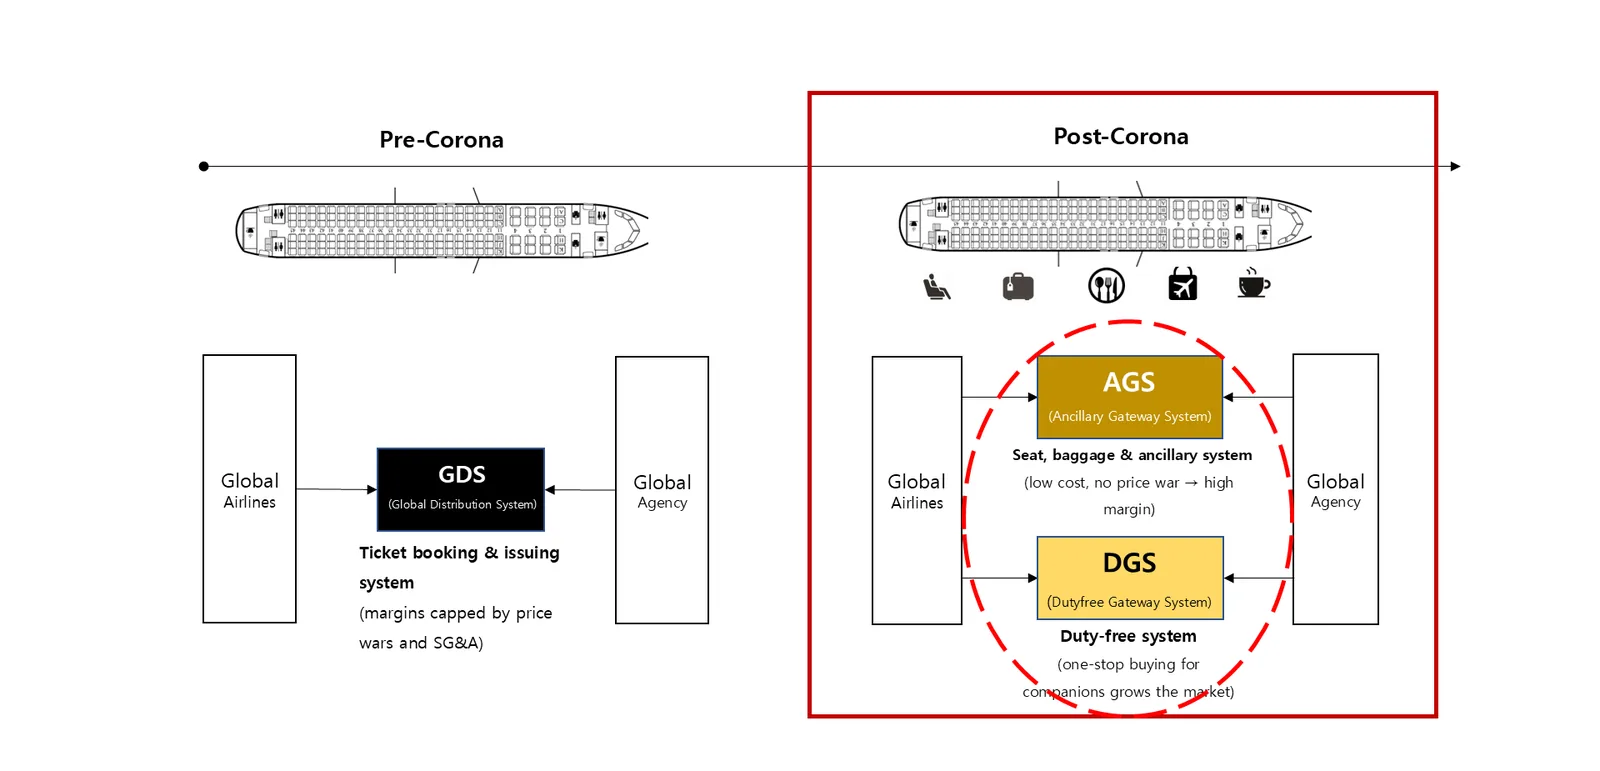
ALLWIN AIR distributes ancillaries between suppliers (airlines and ancillary providers) and sellers (agencies, OTAs and platforms). Each side connects to ALLWIN AIR only once.
Suppliers
- Airlines (seats, baggage, meals, priority baggage, golf packs)
- Travel ancillary suppliers (eSIM, pickup, airport services, duty-free)
ALLWIN AIR AGS
- Airline and NDC API integration, standard conversion
- Display and pricing per seller
- Purchase screens, unified payment
- Customer service, settlement, maintenance
- AI seat recommendation (PNR-based)
Sellers
- Travel agencies and OTAs
- Airline direct channels
- Travel, commerce and payment platforms
→ Travelers buy flights and ancillaries together, inside the seller's own booking flow.
| Aspect | GDS (ticket distribution) | ALLWIN AIR AGS (ancillary distribution) |
|---|---|---|
| Connects | Many airlines ↔ many agencies | Many suppliers ↔ many sellers |
| Products | Ticket booking and issuing | Seats, baggage, meals, priority baggage, golf packs; next eSIM, pickup, airport services |
| Product economics | Heavily price-compared | Low cost of sales, not price-compared, high margin |
| Scope | Booking and issuing | Integration, purchase screens, payment, CS, settlement and maintenance |
Why this position matters now
- Ancillaries are a growing share of airline revenue; leading low-cost carriers earn over 40% of revenue from ancillaries.
- Sellers struggle to make money on tickets alone; ancillaries are a new revenue stream.
- In B2B gateways, whoever builds the connections first becomes the standard. ALLWIN AIR is already connected with 7 Korean airlines and 13 agencies and OTAs.
Frequently asked questions
- What is an AGS (Ancillary Gateway System)?
- A B2B unified sales system that connects many airlines and ancillary suppliers with many sellers to distribute ancillaries — the ancillary counterpart of a GDS for tickets. ALLWIN AIR operates it.
- Does ALLWIN AIR compete with GDSs?
- No. A GDS connects ticket booking and issuing; ALLWIN AIR connects the ancillary sales that follow. Sellers keep their ticket flow and add ALLWIN AIR on top.
- Why couldn't agencies sell ancillaries before?
- Each airline has different systems and rules for ancillaries, so agencies had to integrate and operate each airline separately. ALLWIN AIR does that integration and operation in one place.
Start integrating with ALLWIN AIR
Airlines and ancillary suppliers, as well as travel agencies, OTAs and travel platforms, can all start with a single integration. We agree on the integration model and schedule to fit each partner.